Why Absolute Dispersion Values Distort Screener Logic
Screening across multiple equities using raw dollar ranges or unadjusted volatility coefficients frequently produces a false sense of precision while hiding severe structural biases.
When an analyst establishes a query requiring a minimum Average True Range of three dollars, the filter inherently favors high-dollar equities while completely discarding lower-priced equities exhibiting massive relative expansions. A three-dollar move on a three-hundred-dollar stock represents a mere one percent oscillation, whereas that exact dollar range on a twenty-dollar stock constitutes an extraordinary fifteen percent expansion. Without scaling ATR relative to underlying closing prices, the screener answers a question about nominal price size rather than actual volatility behavior.
This distortion compounds when combining absolute dollar metrics with bounded oscillators. High-nominal instruments dominate the resulting candidate sets, creating an unintended selection bias toward mega-cap liquid names or high-dollar growth stocks. Systematic researchers eliminate this defect by expressing price excursion metrics as percentages of current price or through standardized rolling volatility measures.
Need to Standardize Filter Ratios for Multi-Asset Universes?
Explore our reference models for converting dollar ATR, Bollinger bandwidth, and historical deviation into cross-comparable percentile distributions.
Four Core Normalization Frameworks for Technical Filters
Transforming raw volatility indicators into scale-invariant variables requires selecting a mathematical model aligned with the research hypothesis. Different normalization models solve distinct analytical dilemmas.
- Percentage ATR (NATR)
- (ATR / Close) × 100
- Rolling Z-Score
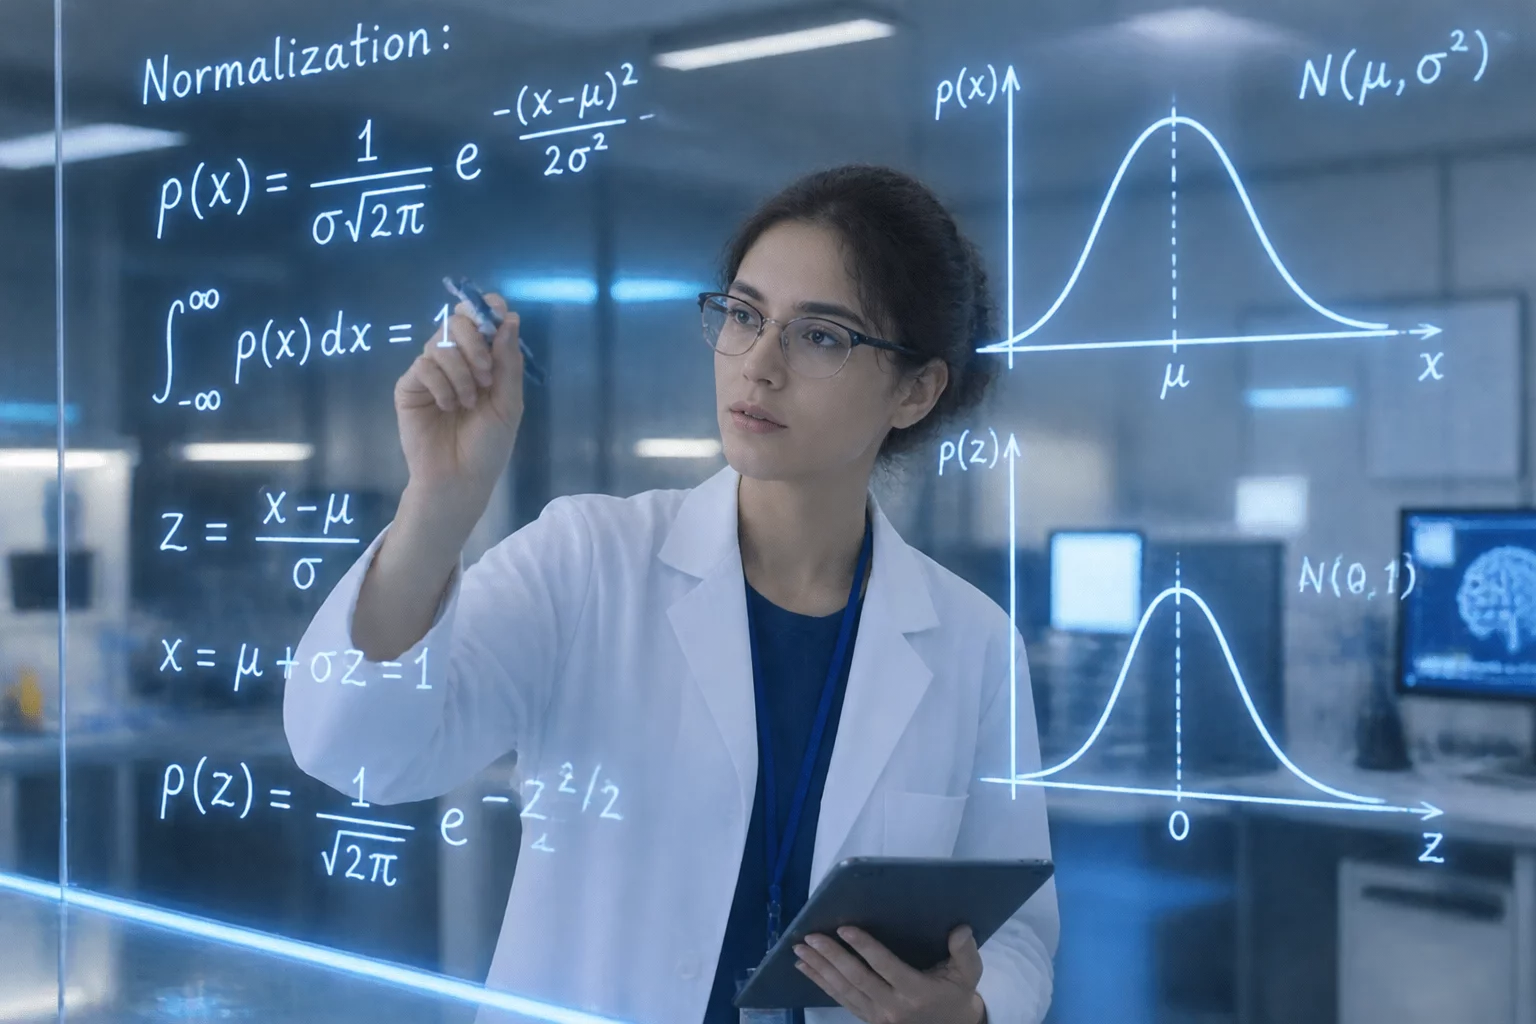
- (X - μ) / σ (63-Day)
- Percentile Ranking
- PercentRank(Metric, 252)
- Min-Max Rescaling
- (X - Min) / (Max - Min)
Normalized ATR (NATR) resolves the nominal share price conflict by translating dollar ranges into basis points or percentage units. However, NATR alone does not clarify whether a three percent daily movement is historically normal or anomalous for a specific instrument. To evaluate whether current volatility represents an outlier relative to an asset's personal baseline, analysts employ rolling lookback percentiles or standard deviation z-scores over 63 to 252 trading sessions.
“A screener filter that compares raw dollar fluctuations across unstandardized assets does not measure volatility. It merely measures share price.”
Percentile Transforms versus Rolling Z-Scores in Practice
Deciding between rolling z-scores and percentile ranks hinges on how your screener handles distribution tails and fat-tailed asset behavior. Financial returns rarely adhere to clean Gaussian bell curves, meaning extreme outlier days can dramatically skew a standard deviation calculation.
Rolling percentile ranking converts any metric into an intuitive range bounded between zero and one hundred. An equity registering an IV Percentile of 92 immediately informs the investigator that current implied volatility exceeds 92 percent of all daily readings captured during the preceding 252 trading sessions. Because percentile ranking is non-parametric, fat-tail anomalies do not distort historical baselines, making it far more robust across broader market baskets than classical z-scores.
Lookback Horizons and Cross-Universe Verification Checks
Selecting an improper lookback horizon can completely invalidate a normalized filter. A twenty-day rolling window responds swiftly to immediate momentum shifts but lacks sufficient historical context to establish whether a range expansion is truly extraordinary. Conversely, a multi-year lookback risks incorporating obsolete regime states where the asset possessed entirely different operational capitalization. Standard workbook protocol recommends maintaining secondary sanity checks and verifying that screener rules do not conflate structural regime changes with cyclical volatility spikes.